Hail and Wind Roof Damage in Humble, TX
After a storm, the order you do things in matters for your insurance claim. Here are the steps from Texas regulators, and how to get a roofing company out to look.
Call (832) 990-6597- Connects you with a participating local company
- Texas insurance and contractor facts from state sources
- Availability depends on the time of day
The first 24 hours after a storm
In short: report the damage to your insurer quickly, document it, make only the temporary repairs needed to stop more damage, and be there when the adjuster visits.
| Step | What the Texas Department of Insurance says |
|---|---|
| Report | File an insurance claim as soon as you can after hail or strong winds damage your home |
| Document | Take pictures and video, and list damage inside and outside; do not throw damaged items away until your company tells you |
| Protect | Remove standing water and cover broken windows and holes to keep rain out; save all receipts, because your policy may pay for temporary repairs |
| Meet the adjuster | Be available for the adjuster visit so the adjuster sees everything |
| Keep records | Keep a list of everyone you talk to at your insurance company |
| Living expenses | If you cannot stay in your house, most policies cover some related expenses; keep your receipts |
Source: Texas Department of Insurance: Hail damage to your home or car? What to do next.
Hail damage is not always obvious
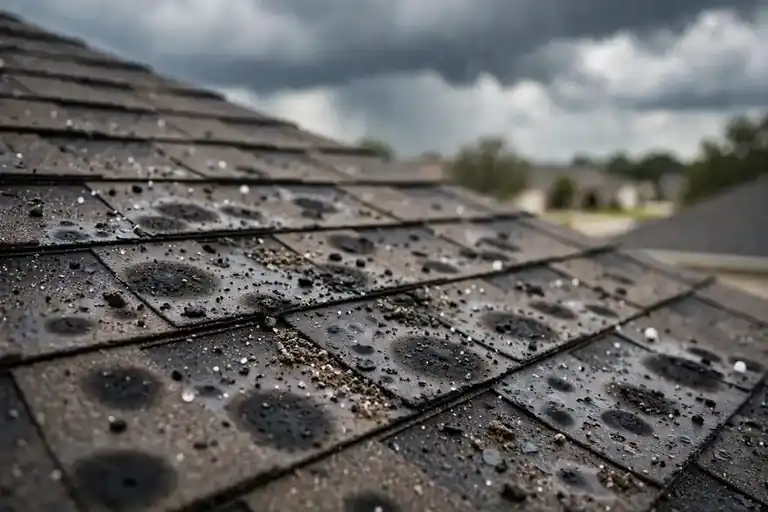
Hail can bruise and crack shingles in ways that are hard to see from the ground, so a roof can look fine and still be damaged.
The Texas Department of Insurance suggests checking your roof for missing or damaged shingles after every storm and hiring a roof inspector every few years. An Insurance Council of Texas spokesperson told NBC 5 that with golf ball size or larger hail, a roof inspection is worth having because there may be serious damage.
Sources: Texas Department of Insurance: Insurance and your roof; NBC 5 Responds: If you have hail damage, what's next?.
Wind and hail deductibles
A deductible is the amount you must pay before your company pays. The Texas Department of Insurance says to ask your agent whether the deductible for wind and hail damage is different from the deductible for other damage. If it is, you might pay more out of pocket when a storm damages your roof.
Two more points from the same guidance: some policies pay up to the full amount needed to repair the roof (called replacement cost coverage), while others pay less if the roof is older or showing wear (called actual cash value coverage). And with replacement cost coverage, the company pays with two checks, the second after repairs have started.
Source: Texas Department of Insurance: Insurance and your roof.
After a storm, watch out for door-knockers
The Texas Department of Insurance warns that out-of-town scam artists may be the first to arrive at your door after a disaster. Its advice is to hire local contractors, get written bids and check references.
- Get more than one bid, and compare them.
- Do not pay in full up front, and do not make the final payment until the work is done.
- Walk away from anyone who offers to waive your deductible. It is illegal in Texas.
- Never sign a contract with blank spaces.
Our guide to hiring a roofer in Texas covers contracts, down payments and red flags in more detail.
Sources: Texas Department of Insurance: How to avoid contracting scams; Texas Department of Insurance: Hail damage to your home or car? What to do next.
Storm damage questions
How soon should I file a hail damage claim?
As soon as you can. The Texas Department of Insurance says to file a claim quickly after hail or strong winds damage your home, and that your insurer should pay for hail damage if you have wind and hail coverage on your home policy.
How do I know if hail damaged my roof?
Some damage is easy to see, and some is not. An Insurance Council of Texas spokesperson told NBC 5 that with golf ball or larger hail it is worth having the roof inspected because there may be serious damage. After any storm, check for missing or damaged shingles.
Should I be home for the adjuster?
Yes if you can. The Texas Department of Insurance says to be available for the adjuster visit so you can make sure the adjuster sees everything.
Can a contractor take over my claim?
Be careful. The Texas Department of Insurance warns against signing contracts that say you agree to repairs for the value of insurance proceeds, because the contractor then gets every penny of your insurance payment. Read everything before you sign, and never sign with blank spaces.
Does a storm claim cover somewhere to stay?
Possibly. The Texas Department of Insurance says that if you cannot stay in your house after a storm, most policies cover some related expenses. Keep your receipts and ask your insurer about living expenses.
Storm damage on your roof? Call now.
Independent referral service. Participating companies pay us for referrals. Calls may be recorded. An automated prompt asks for your ZIP code to match your call with a company in your area.